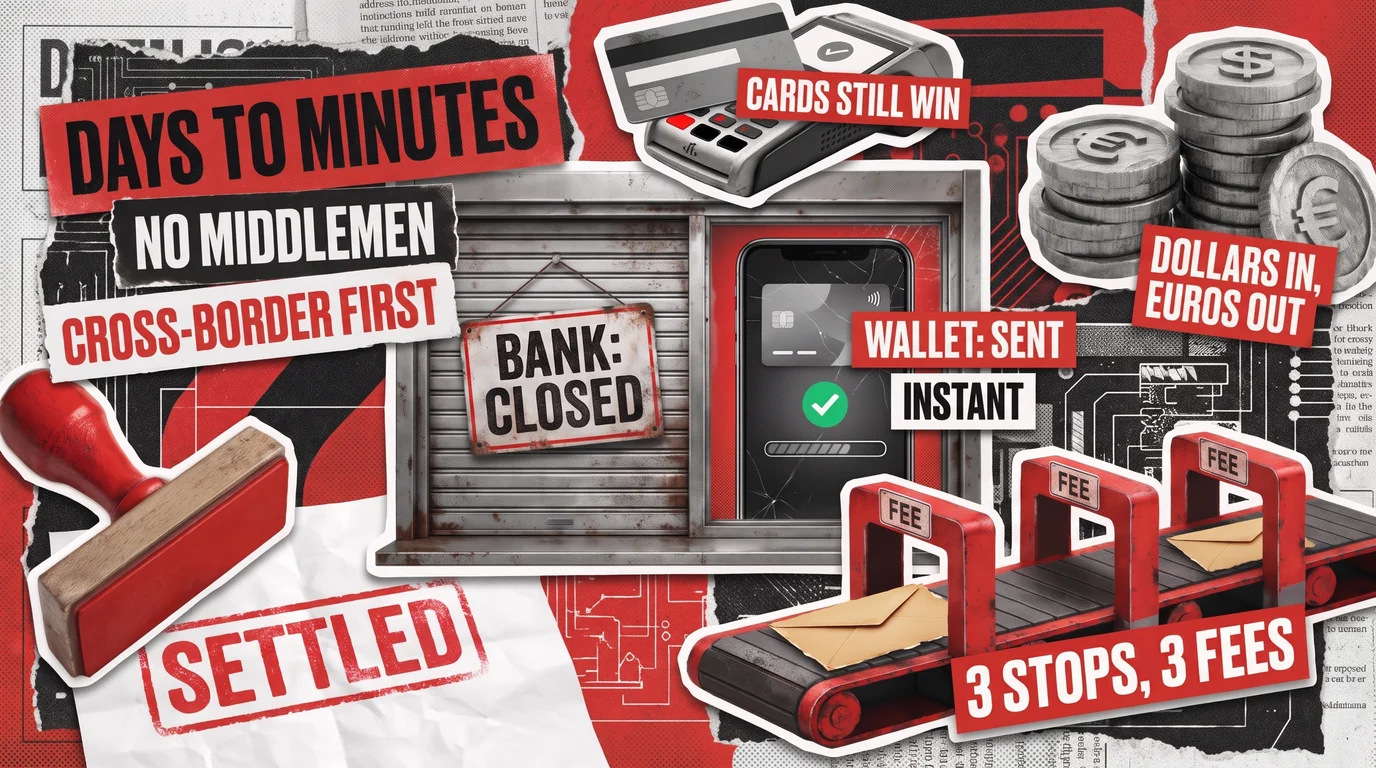
Blockchain for payment processing is most useful where money passes through several banks before it arrives: cross-border transfers and large payments between companies. On those routes, a blockchain removes the middle steps and cuts settlement from days to minutes. Everyday checkout purchases already run well on cards and instant bank transfers, so the gains come from choosing the right payment flows.
Payment systems of this kind belong to decentralized finance (DeFi), and they are a core part of our DeFi development services. The value of such systems for a business is easy to count in days saved and bank fees avoided, which puts payments among the easiest blockchain financial services to justify. However, if you move the wrong kind of transaction to blockchain, you add licensing work and extra steps for customers without making payments any faster. This article will help you avoid that. Redwerk’s engineers will explain where blockchain technology helps and where traditional payments still do better.
What Does Blockchain Payment Processing Remove?
Most of the middlemen disappear: the banks that pass money along and the services that convert one currency into another. Take a business that pays a supplier in euros from a dollar account. With traditional payments, the company’s bank sends the payment, a currency exchange service converts the dollars, and the supplier’s bank credits the account. All three charge for their part. Card payments have the same layers, and overlooking currency markups on cross-border card charges is one of the common payment gateway integration mistakes.
On a blockchain, the payment moves directly from the company’s digital wallet to the supplier’s wallet. The blockchain network itself delivers the money, so no bank needs to forward it. Both sides can see the completed transfer in the network’s records. The conversion happens in the same transaction, as the system swaps dollar tokens for euro tokens before they reach the supplier.
The tokens in such payments are stablecoins, which are designed to keep the same value as a regular currency, such as the US dollar or the euro. Businesses prefer them to Bitcoin because the amount stays the same between sending and receiving. A supplier who receives 10,000 euros in a euro stablecoin still holds the same amount the next morning.
Redwerk builds payment and currency exchange tools that work this way, from the wallets to the conversion step. Only one outside service is still needed: a licensed partner that turns the company’s dollars into tokens and later pays the supplier’s euros into a bank account.
Where Does Blockchain for Payment Processing Work Best?
Cross-border transfers and large payments between businesses gain the most, because traditional banking on those routes is the slowest and most expensive. In some countries, such a payment takes up to five business days, since each bank processes transfers only within set hours and in scheduled batches.
According to the Financial Stability Board, which monitors international payment speed for the G20, fewer than 45% of payments sent by businesses abroad settled within one business day in 2025.
On a blockchain, a payment on the same route arrives in seconds or minutes, at any hour and on any day of the week. That speed matters most in these situations:
- Paying suppliers abroad: A factory in another country receives the money the same day, so goods can ship sooner.
- Moving cash between subsidiaries: A company with offices in several countries can shift funds over a weekend without waiting for banks to open.
- Large payments between companies: Faster settlement shortens the time a big sum spends in transit, which lowers the risk of losing it if either side goes bankrupt before the transfer completes.
- Paying many recipients at once: Freelancers, sellers, or partners in different countries get paid from one system instead of through dozens of bank relationships.
Large payment networks already use blockchain behind the scenes. Visa lets partner banks settle card transactions in stablecoins. In 2026, that payment flow reached a pace of over $20 billion a year, over 15 times more than in 2025. Some financial institutions that settle large sums with each other use a closed network that admits invited members alone. Building such systems is the job of private blockchain development.
Can Smart Contracts Split a Payment Automatically?
A smart contract can divide incoming money among several recipients the moment it arrives. This code holds the payment rules and runs on the blockchain itself. For example, a marketplace can send each seller’s share and keep its commission in the same transaction. Nobody has to run manual payouts at the end of the month. A simpler version of this rule runs in Tingl, a private messaging app our team developed from scratch. When a user sends a paid “superlike,” the author of the message receives a reward automatically. Comparable rule-based payouts appear in blockchain marketing use cases and in insurance claims settled by smart contracts.
Where Do Cards and Instant Bank Transfers Still Win?
For everyday purchases, shoppers already have fast, familiar options that protect them if something goes wrong. When you compare blockchain payments vs traditional options at a store checkout, most of the advantages disappear:
- Speed the shopper sees: A card payment is approved in a few seconds. The slower settlement between banks happens later, out of the customer’s sight.
- Local transfers: In the US, instant payment systems such as FedNow and the Real-Time Payments network move money between bank accounts in seconds, around the clock. SEPA Instant does the same in the EU.
- Disputes and refunds: Card customers can ask their bank to reverse a wrong or fraudulent charge. A confirmed blockchain transfer is final, so a refund requires a new payment from the merchant.
- Setup for customers: Paying with stablecoins requires a digital wallet and a balance in it, which most shoppers don’t have.
Small payments can still work well on a blockchain inside apps whose users already hold crypto. For instance, Tingl users pay for private content in the chat itself. We chose the Polygon network for that app partly because of its lower transaction fees. On a network with high fees, a small payment can cost more to send than it’s worth.
What a business has to handle depends on the type of payment:
Card purchase at checkout
A processing fee on every sale
Every shopper needs a crypto wallet, and each refund is a new payment
Card
Routine transfer within one country
A small fee on each transfer
No time saved, plus an extra step to convert tokens into local currency
Instant bank transfer
Supplier payment abroad
Bank fees, a currency conversion markup, and days of waiting
Minutes to arrive, if the supplier accepts stablecoins
Blockchain
Large payment between companies
Transfer fees and money tied up in transit
Both companies agree on a network and run compliance checks
Blockchain
Payouts to many countries
Bank fees and a separate account in each country
One system for all recipients, if they can cash out locally
Blockchain
What Holds Back Blockchain Payment Adoption?
Price swings and unclear rules are the two concerns that slow adoption most. Paying in stablecoins instead of Bitcoin removes most of the price risk, though not all of it. In March 2023, a major stablecoin briefly fell below one dollar after its issuer reported that part of its reserves sat in a failed US bank. For that reason, payment systems usually convert incoming tokens to local currency quickly and keep only the balance they need.
Regulation differs by country and is still changing:
- United States: The GENIUS Act requires companies that create stablecoins to hold a license. From July 2028, US platforms may offer only licensed coins, so a business should choose one whose maker expects to qualify. In New York, any partner that holds or moves crypto for your customers also needs the state’s BitLicense.
- European Union: Under the Markets in Crypto-Assets regulation (MiCA), a stablecoin can be offered in the EU only if its issuer holds an authorization. In October 2026, the EU’s securities regulator told crypto service providers to stop serving local clients with any other coins. A payment flow serving European customers therefore depends on the coin as much as on the software. Our MiCA regulation compliance team can check whether your flow also needs an authorization of its own.
Your legal advisors confirm which rules apply in each market you serve. Our engineers then build those rules into the payment software as part of our blockchain development services. We tailor the package to each client’s specific needs.
What Does a Blockchain Payment Project Involve?
Most projects follow the same seven steps, from choosing a first route to a small test run:
- Pick one payment flow. Supplier payments to a single country are a common first choice. Note the current delivery time and fees for that route.
- Choose a network and a stablecoin. Compare transaction fees, confirmation speed, and the coins your partners accept.
- Decide who holds the funds. A licensed company that stores crypto for businesses can hold them for you, or your team can manage its own wallet. Apps that hold customer money face the same choice on a larger scale, as our guide to crypto banking app development explains.
- Plan how the money reaches bank accounts. The conversion partner you pick sets which currencies and countries you can pay out to. If users will also trade coins on your platform, expect a larger budget, because cryptocurrency exchange app development cost covers far more than payments.
- Build in compliance checks. The system verifies customer identities and screens wallet addresses against sanctions lists before any money moves.
- Connect to your accounting software. Every blockchain payment needs to match an invoice, so your finance team sees the same totals as the network records.
- Start with small payments. Run a few low-value transfers on the new route and compare their delivery time and fees with the figures you recorded in the first step.
Is Blockchain the Right Choice for Your Payments?
Blockchain for payment processing is the right choice for the transactions that cost your business the most time and money. Usually, they pass through several banks or a currency exchange service and take days to arrive. Everyday card purchases and small domestic transfers already work well on the systems you use now.
Select a slow, costly payment whose receiver can accept stablecoins and cash them out locally. Then, our DeFi engineers can move it to blockchain and link the whole thing to your existing bank and accounting software. The rest of your finance work stays the same.
Ready to adopt this type of blockchain tech? Talk to our team today!
FAQ
How does blockchain for payment processing work?
Blockchain for payment processing replaces the banks in a transfer with a network of independent computers. When a business sends money, these computers check that the sender’s digital wallet holds enough funds, record the payment, and credit the receiver’s wallet, usually within minutes. Each of them keeps an identical copy of the record, so no bank has to vouch for it.
Are blockchain payments faster than bank transfers?
Blockchain payments are faster for sending money abroad and at night or on weekends. Traditional transfers wait for banks to open, and an international one may pass through several institutions. A blockchain network runs around the clock, and money sent over it usually arrives in a few minutes. Within one country, the gain is small, since instant payment systems in the US and Europe already move funds in seconds.
What is a stablecoin payment?
A stablecoin payment moves digital tokens that are each worth one unit of a regular currency, most often the US dollar. The issuing company keeps cash and short-term government bonds in reserve and swaps each coin back at full value on request. This backing lets a business pay in crypto without the price swings of coins such as Bitcoin.
Can a blockchain payment be reversed?
Once the network confirms a blockchain payment, nobody can cancel it, not even the sender. Businesses protect themselves in other ways. Their software checks each destination address before sending, a small test transfer goes out before a large one, and refunds are sent as new transactions. These habits matter because funds sent by mistake usually can’t be recovered.
Do businesses need a license to use blockchain payments?
Licensing rules for blockchain payments depend on the role a business plays. A company that only pays its own suppliers in stablecoins usually works through a regulated payment provider and needs no permit of its own. Keeping or sending crypto on behalf of customers typically requires a state money transmitter license in the US or MiCA authorization in the EU. Legal advice for each market should confirm the details.
See how we boosted Orderstep subscription revenue by building a premium webshop module